
Every year when I come to London, I find myself thinking about why I like this city so much.
Perhaps some of it goes back to 1985, when I studied at Oxford for a semester and visited London for the first time. There is something powerful about returning to a place you first experienced when you were young, when so much of the world was still new.
But I think there is more to it than nostalgia.
I love London’s pub culture. I love its grittiness and hustle and bustle. I love navigating the Tube and buses. I love moving through neighborhoods that feel completely different from one another. I love the history, the diversity, and the juxtaposition of buildings hundreds of years old with modern towers rising above them.
London feels fully alive to me. And somehow it never gets old.
This year, someone finally gave me a way to understand why.
I was talking with one of our relationship managers at EPIC, our insurance broker, who has probably been to London more than 100 times and has also spent considerable time in Paris. I asked which city she preferred, particularly for a longer stay.
London.
When I asked why, her answer was essentially:
Paris is about indulgence. London is about purpose.
That really landed with me.
Obviously, this is an enormous generalization. Paris is magnificent. Its museums, restaurants, shopping, and almost impossibly beautiful and uniform architecture are extraordinary. But after a while, I start to feel restless there. I begin to hunger for something else.
Purpose.
London gives me that feeling almost immediately. Perhaps it is because I spend so much of my time in the City, going from one insurance office to another and visiting Lloyd’s. People seem to be moving with intention. There is an unmistakable air of business, commerce, deals, networking and risk-taking.
Everyone seems to be going somewhere.
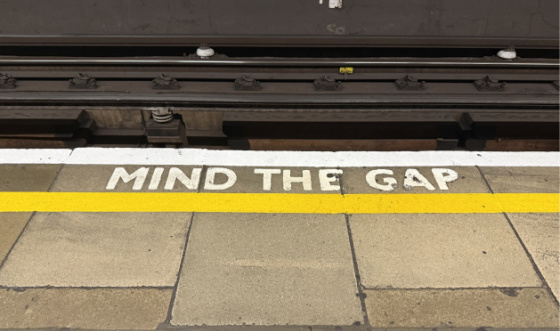
And on this trip, as I moved around London having more than ten meetings with insurance companies and Lloyd’s syndicates, I kept seeing three famous words everywhere I went:
It occurred to me that I couldn’t think of a better description of what we are doing at CWS right now.
We are minding the gap.
Actually, we are minding two of them.
The Cash-Flow Gap
The first is the gap between the cash flow apartment properties generated under the assumptions of the previous cycle and what they are generating today.
For years, apartment owners benefited from an extraordinarily favorable combination: low interest rates, strong rent growth, appreciating property values, and readily available leverage.
Then several things changed at essentially the same time.
Interest rates increased dramatically. A huge wave of new apartment construction began delivering. Rent growth slowed or turned negative in some markets. Developers began offering substantial concessions to fill newly completed properties. And many operating expenses remained stubbornly elevated.
The result is straightforward: revenue has not kept pace with expenses and the cost of capital.
This is not an abstract financial problem. It shows up every month at the individual property level.
And because an apartment community contains a finite number of units, there is no magical lever an operator can pull to manufacture enough additional revenue to make the gap disappear.
You have to mind it.
That means operating better. Watching expenses. Focusing relentlessly on occupancy and resident retention. Investing intelligently in the physical asset. And, when necessary, preserving cash rather than distributing it.
That last point is particularly important.
CWS has suspended distributions at certain properties because we refuse to preserve today’s distribution by compromising tomorrow’s asset.
Roofs still have to be replaced. Air-conditioning systems still fail. Pipes still break. Life-safety work still has to be completed. Residents still deserve well-maintained homes.
Preserve the asset first.
Ultimately, the distribution comes from the asset. Sacrificing the latter to protect the former gets the hierarchy backward.
The Leverage Gap
The second gap may ultimately prove even more consequential.
The apartment industry has too much debt relative to what many properties can support in today’s interest-rate environment.
Loans originated when rates and debt-service costs were substantially lower are now maturing into a very different world. Even properties that are fundamentally good real estate can find that the proceeds available from a new loan are significantly less than the debt being refinanced.
That difference has to come from somewhere.
And increasingly, it has to come from equity.
This is the leverage gap.
I found myself discussing this repeatedly in London because I think deleveraging will be one of the defining features of the next several years in the apartment industry.
Ironically, I also think it will create one of the biggest opportunities.
Owners who need leverage will find this environment extremely challenging. Owners and investors with access to substantial pools of patient equity can approach the same environment very differently.
I increasingly believe that the big winners of the next apartment cycle may not be those with access to the most debt.
They may be those who need debt the least.
That is a profound reversal from much of the previous cycle.
And it leads to something I have been thinking about a great deal: the enormous potential advantage created by what I would call the leverage gap.
The industry needs to deleverage. Somebody has to provide the equity that makes that deleveraging possible.
We want CWS to be positioned to do exactly that.
Mind the Gap, Don’t Fear It
The more I thought about the Underground warning, the more appropriate the wording became.
It doesn’t say:
Fear the gap.
It doesn’t say:
Avoid the gap.
It says:
Mind the gap.
There is a meaningful difference.
The gap is simply a condition that exists. The danger comes from failing to recognize it or pretending it isn’t there.
That is true of the space between the train and the platform, and it is equally true of investing.
We have no interest in minimizing the difficulties facing the apartment industry. We would obviously prefer that many of these challenges had never materialized. But wishing they didn’t exist doesn’t change the reality.
Our job is to see the gaps clearly and respond appropriately.
That means minding cash flow.
Minding leverage.
Minding liquidity.
Minding maturities.
Minding capital expenditures.
And, perhaps most importantly, minding the asset itself.
The Cure for High Rents May Have Been High Rents
Fortunately, markets contain their own corrective mechanisms.
The enormous amount of apartment construction we are currently absorbing didn’t appear out of nowhere. It was the response to extraordinary rent growth and attractive development economics.
Eventually, the industry did what capitalism invariably encourages it to do when returns appear unusually attractive:
It produced more.
Much more.
Now the economics have reversed. Construction costs remain high. Financing costs are dramatically higher. Rents in many places are under pressure from the very supply that previous economics encouraged developers to build.
In many markets, rents would need to be dramatically higher to justify significant amounts of new construction.
The development pipeline is therefore contracting.
This doesn’t make the current supply disappear. Real estate operates with long lags, and apartments already under construction still have to be completed and absorbed.
But today’s difficult economics are sowing the seeds of tomorrow’s recovery.
This is one reason I increasingly see the current environment not simply as a period to endure, but as a transition to prepare for.
We have to mind the gap long enough to reach the other side.
From Financial Engineering to Operating Engineering
The nature of that preparation is also changing.
For much of the prior cycle, declining interest rates and rising asset values could compensate for a surprising number of mistakes. Financial engineering was enormously powerful.
Today, operating engineering matters much more.
We don’t want to buy problems merely because they appear cheap.
Some of the “opportunities” emerging today involve older assets with years of deferred maintenance, compromised resident profiles, and significant future capital requirements. A low price per unit does not necessarily mean something is inexpensive.
We would much rather own good real estate purchased from a motivated seller than inherit someone else’s accumulated physical problems.
I think of the distinction this way:
Distress in the capital structure can create opportunity. Distress in the physical asset can create headaches.
That distinction will matter enormously in the years ahead.
Insurance Is Another Exercise in Minding the Gap
Of course, the reason I was in London was insurance.
And the more I thought about it, the more I realized that insurance itself is fundamentally about minding gaps.
There is a gap between risks we know exist and our ability to predict when they will materialize.
There is a gap between risks we want to retain and those we want someone else to assume.
There is a gap between what something costs to insure and what it might cost not to insure it.
Our meetings this year suggested that the property insurance market has clearly become more competitive. After several extremely difficult years, additional capital and capacity started putting downward pressure on pricing beginning in 2024 and will continue into 2026.
But cheaper insurance doesn’t eliminate the need for thoughtful risk management.
In fact, our experience has taught us the opposite.
After suffering significant freeze losses during prior winter storms, we invested millions of dollars hardening properties, insulating piping, addressing vulnerable areas, and developing protocols with local fire departments that allow us to drain and depressurize certain sprinkler systems during extreme freeze events.
Those investments were subsequently tested.
At the properties where the protocols were activated during a later freeze, we experienced no freeze losses.
To me, that is what good risk management looks like.
It isn’t pretending the gap doesn’t exist.
It is learning exactly where the gap is and changing your behavior accordingly.
The same thinking is now informing our increased focus on moisture detection and mold prevention.
Insurance is important.
Prevention is better.
Relationships Matter Too
There is another reason we continue coming to London rather than treating insurance as a commodity to be purchased through a spreadsheet.
CWS has been placing insurance in the London market for many years. Over that time, we have built relationships with underwriters who understand our portfolio, our operating philosophy and, importantly, how we respond when things go wrong.
Insurance is one of those peculiar businesses in which you don’t really learn the quality of the product when you purchase it.
You learn when something bad happens.
The same is true of relationships.
When times are easy, capital can feel commoditized. So can lenders, insurance carriers, investors, and business partners.
It is when conditions become difficult that the differences become obvious.
Perhaps relationships are another form of gap we have to mind: the distance between a transaction and a genuine partnership.
Purpose
Which brings me back to the distinction between London and Paris.
Indulgence versus purpose.
The apartment industry had a long period in which the economics allowed for a certain amount of indulgence.
Debt was extraordinarily cheap.
Leverage was abundant.
Values appreciated.
Development proliferated.
Mistakes could be refinanced.
Then the gaps opened.
Today the environment is demanding something else from us.
Purpose.
Discipline.
Patience.
Liquidity.
Operational excellence.
Stewardship.
And humility.
Walking through London, particularly through the City and Lloyd’s, I find myself energized by precisely those qualities. The city has an extraordinary history, but it doesn’t seem to spend much time admiring itself. People are moving. The Tube is crowded. The buses are moving. The pubs are full. Deals are being discussed. Risk is being priced. Capital is constantly looking for somewhere productive to go.
London somehow manages to feel ancient and restless at the same time.
Maybe that’s why I love it.
Paris can tempt me to linger.
London makes me want to get moving.
And yet, before getting on the train, London offers one very important piece of advice.
Mind the gap.
That feels like pretty good advice for the apartment industry right now too.

Leave a Reply